Are you tired of feeling lost in the maze of insurance options in North Carolina? You’re not alone! Navigating the world of insurance can be overwhelming, especially when you’re trying to secure the best rates. But don’t worry; we’re here to demystify the process and help you get the coverage you need at a price that won’t break the bank.
At Backlinko, we believe an informed consumer is a powerful one. This guide will take you step-by-step through the types of insurance, factors affecting rates, tips for finding the best deals, and more. By the end of this article, you’ll feel confident and empowered to make the best insurance decisions for your needs.



Overview of Insurance Types in NC
Did you know that choosing the right insurance policy can be as complex as a jigsaw puzzle? The good news is, North Carolina offers a wide range of insurance types that cater to different needs.
You’ll find health, auto, home, and life insurance here. But each comes with a unique twist to suit specific circumstances. Let’s dig deeper into what these types really mean for you.
Health Insurance: Cushioning Your Medical Expenses
Health insurance in NC is a must-have. North Carolinians can choose from a variety of plans. Some include high-deductible options perfect for young, healthy individuals. Others offer comprehensive coverage, which is ideal if you have frequent medical needs or a larger family.
- Preferred Provider Organization (PPO): Flexible and significant provider choice.
- Health Maintenance Organization (HMO): Lower costs with a restricted network.
- Exclusive Provider Organization (EPO): No out-of-network coverage, often more affordable.
- High-Deductible Health Plans (HDHP): Lower premiums, ideal for less frequent healthcare users.
Pro Tip: Not sure which one is right for you? Crunch the numbers based on your past medical expenses to zero in on the best plan.
Auto Insurance: Protecting You On The Road
Auto insurance in NC isn’t just a legal requirement; it’s a safety net. You’ll be safeguarded against unexpected events while driving.
- Liability Coverage: Covers damages or injuries you cause in an accident.
- Collision Coverage: Pays for damages to your own vehicle after a collision.
- Comprehensive Coverage: Protects against non-collision-related incidents like theft or weather damage.
- Uninsured/Underinsured Motorist Coverage: A safety net if you’re hit by someone without sufficient insurance.
Here’s the deal: Auto insurance isn’t just about ticking a box; it’s about choosing coverage that aligns with your driving habits and lifestyle.
Home Insurance: Safeguarding Your Abode
Your home is likely your most valuable asset. Home insurance ensures it stays protected against a myriad of risks.
- Basic Homeowner’s Policy: Covers your home and possessions against natural disasters, theft, and more.
- Condo Insurance: Tailor-made for condo owners, covering personal property and certain building components.
- Renters Insurance: Takes care of personal possessions and liability for renters.
Pro Tip: Review your belongings every couple of years and adjust your coverage as necessary. Your policy should grow with you and your assets.
Life Insurance: Financial Security for Loved Ones
Life insurance provides those we leave behind with the financial safety they need. It’s a plan for the unforeseen future.
- Term Life Insurance: Temporary coverage, affordable for families, with fixed payouts.
- Whole Life Insurance: Permanent coverage with a cash value component.
- Universal Life Insurance: Offers flexible premiums and potentially grows cash value.
Most people don’t realize it, but the key to choosing life insurance is understanding the duration of coverage you need versus the investment component you seek.
Factors Affecting Insurance Rates in NC
Did you know that two drivers with the same car model and driving experience can pay significantly different insurance rates in North Carolina? It’s all about the factors at play. Let’s break down the key elements that impact what you pay.
Insurance rates in North Carolina don’t just hinge on your vehicle or driving history. In fact, there are multiple variables that insurers scrutinize. From your credit score to where you park your car at night, each detail can influence your premium. That’s why it’s vital to understand what’s driving your costs.
Key Insurance Rate Factors
First off, let’s check out the major factors. One of the biggest elements? Your “Location.” If you live in a congested urban area, chances are your insurance costs will be higher due to the increased risk of accidents and vandalism. Then there’s “Driving History.” North Carolina insurers will dig deep into your record, highlighting any past claims or penalties.
Now, onto an often overlooked aspect: “Credit Score.” That’s right! Your financial behavior can dramatically alter your rates. A stellar credit score can earn you a discount, while a poor score might cost you. Pro Tip:
Paying your bills on time can help keep your insurance affordable.
Regulation Impacts
Local regulations also shape the cost. North Carolina’s “Rate Bureau” requires insurers to offer standardized rates, which injects a level of fairness but doesn’t remove all disparities. Insurers may still apply variable factors.
Ever hear of “Territory Rating”? In NC, this means your ZIP code significantly sways your rate due to local crime statistics and accident data. And let’s not forget about those infamous local weather conditions! That’s right, hurricane-prone areas might see higher rates due to potential storm damage.
Comparison of Factors
Here’s a quick comparison of how these elements stack up:
| Factor | High Cost Impact | Low Cost Impact |
|---|---|---|
| Location | Urban, High Crime Rate | Rural, Low Crime Rate |
| Driving History | Accidents, Traffic Violations | Clean Record |
| Credit Score | Poor Credit | Excellent Credit |
| Regulatory Environment | Non-standardized rates | Standardized rates |
The bottom line? Understanding these factors gives you the power to possibly lower your costs. With the right approach, you can take control of what you’re paying and potentially save a bundle. Keep these points in mind when shopping for the best rates!
Tips for Finding the Best Insurance Rates
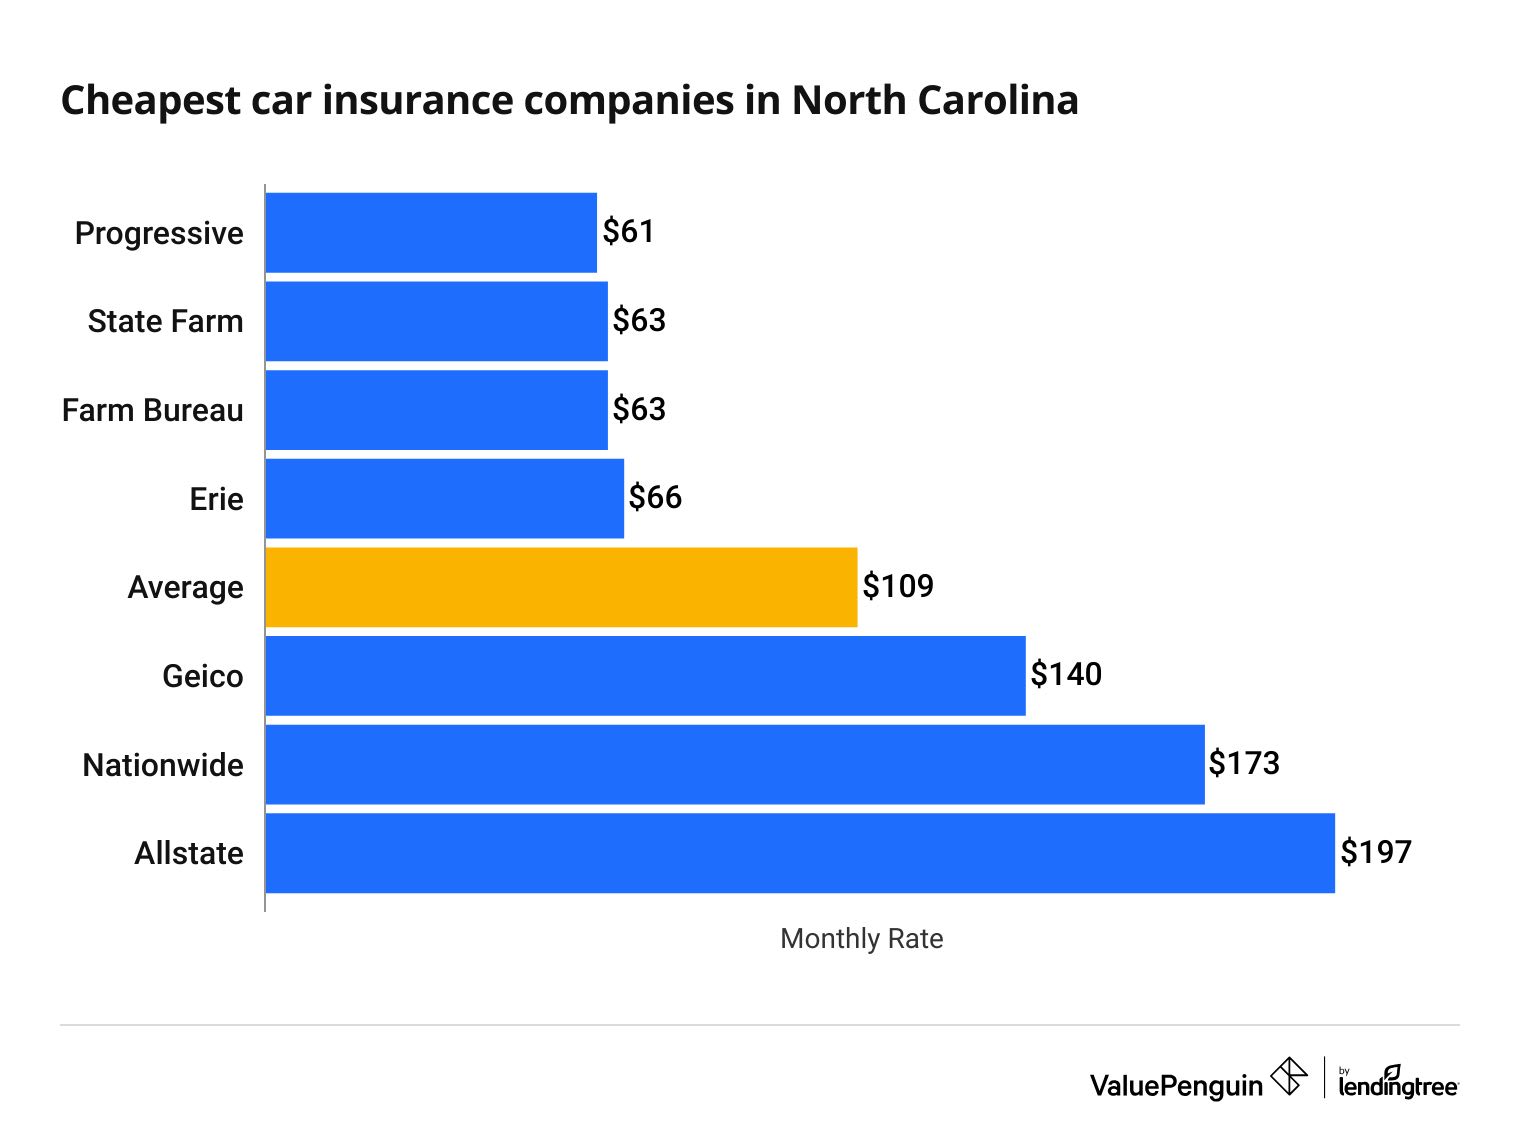
Ever wonder why your neighbor is paying less for the same insurance coverage? Here’s the deal: getting great insurance rates requires strategy. You need to know where to look and what to ask for.
Finding the best insurance rates doesn’t have to be rocket science. You just need a game plan. By following a few key steps, you can uncover rates that fit your budget while maximizing coverage.
Step-by-Step Process to Search and Negotiate Best Rates
Start by looking at what you need. Sounds obvious, right? But many people skip this step and end up overpaying for coverage they’ll never use.
- Step #1: Analyze Your Needs. List what matters most to you. Whether it’s car, health, or home insurance, determine what coverage you truly need.
- Step #2: Compare Quotes Online. Use comparison websites to get a sense of current market rates. This is your baseline and can guide your negotiations.
- Step #3: Contact an Agent Directly. After you have your baseline, speak to an insurance agent. They can provide insights and may have access to discounts that aren’t easily found online.
- Step #4: Negotiate Using Your Research. You’ve done your homework, now leverage it. Don’t hesitate to ask for a better deal based on competitor rates.
Pro Tip: Always ask for additional discounts. You never know what special offers an agent might have up their sleeve!
Strategies to Lower Insurance Costs Without Sacrificing Coverage
Here’s a shocker: 60% of people never ask about discounts. But why leave money on the table?
- Increase Your Deductible. By opting for a higher deductible, you can significantly lower your monthly premiums.
- Bundle Your Policies. Insurers often offer discounts for holding multiple policies with them. Think auto and home insurance together.
- Maintain a Good Credit Score. Many insurers use credit scores to determine rates. A better score can lead to better deals.
- Install Safety Devices. Adding things like burglar alarms or fire sprinklers can result in lower home insurance costs.
Common Mistakes to Avoid During the Insurance Search
Mistakes can cost you, literally. Here’s what you need to steer clear of:
- Not Comparing Enough Quotes. If you only look at one company, you’re missing out. Competitive comparison is key to savings.
- Ignoring Fine Print. Not delving into the details can leave you with insufficient coverage or unexpected expenses.
- Forgetting to Reevaluate Annually. Circumstances change. Check rates yearly to see if you can snag a better deal.
“Knowledge is power when it comes to insurance shopping. Use it to save smart!”
Top Insurance Providers in North Carolina
Looking for the best insurance in North Carolina can feel like a full-time job. With so many options, how do you decide?
Don’t sweat it. I’m here to break it down for you. Let’s dive into the top insurance providers that have got North Carolina buzzing. We’ll look at their features, coverage options, and, most importantly, how they treat their customers.
Leading Providers Offering Comprehensive Coverage and Stellar Service
It’s no secret that the insurance landscape in North Carolina is competitive. Here’s the deal: some providers really stand out for their coverage options and customer support. Let’s look at the leaders:
- State Farm
- Features: Robust coverage plans, excellent customer service ratings.
- Coverage Options: Offers everything from auto and home to life and health insurance.
- Customer Service: Known for personalized support and quick response times.
- GEICO
- Features: Competitive pricing model, user-friendly mobile app.
- Coverage Options: Specializes in auto insurance with availability of renters and home insurance.
- Customer Service: 24/7 customer service with a satisfaction guarantee.
- Nationwide
- Features: Broad insurance products, multi-policy discounts.
- Coverage Options: Inclusive of property, casualty, and investment products.
- Customer Service: High ratings for claims satisfaction and accessibility.
Coverage Comparison Across Top Providers
A key aspect of choosing an insurance provider is understanding the subtle yet critical differences in their offerings. Check out this comparison:
| Provider | Specialization | Coverage Extras | Customer Support |
|---|---|---|---|
| State Farm | Auto, Home, Life | Discounts for multiple policies | 24/7 phone support |
| GEICO | Auto | Mobile app convenience | Round-the-clock service |
| Nationwide | Multi-line Insurance | Investment products | Online and local agent support |
Profile Description Template for Each Provider
You need a quick summary of what each insurer is all about. Here’s a handy profile template:
[Provider Name]: A trusted choice for [Focus Area, e.g., auto insurance]. Known for [Unique Feature], they offer [Variety of Coverages]. Customer service is [Service Quality, e.g., rated highly] because of [Reason]. They provide excellent value with [Discounts or Special Offers].
Pro Tip: It’s not just about the price—ensure you’re getting the coverage that fits your needs!
Customer Reviews and Testimonials
Ever wonder what real customers think about insurance providers in North Carolina? You’re not alone. Customer reviews can reveal the hidden strengths and weaknesses of insurance companies.
Here’s the deal: user experiences offer valuable insights that can help you make informed decisions. But not all feedback is created equal. By sifting through numerous reviews, you can identify patterns that consistently highlight excellent service—or expose areas where insurers might fall short.
Common Experiences with NC Insurance Providers
Many customers laud providers for their swift claim processing, a crucial factor when selecting an insurer. Conversely, high premium costs are a recurring grievance. Let’s delve deeper into specifics. Some insurers like State Farm are praised for their dedicated agents, while others face criticism for lackluster customer service.
“Geico saved me thousands over the years. They’ve always been prompt and straightforward with claims.” – Jack R.
“I experienced nothing but delays and hidden fees with my last provider. Wish I’d switched sooner!” – Amy L.
Pro Tip: Look for companies with consistently positive feedback on customer support; they tend to handle claims faster and more efficiently.
Patterns Highlighting Deficiencies and Merits
Customer reviews frequently emphasize quick response times as a merit in the NC insurance landscape. On the flip side, clients often express frustration with unexpected rate hikes. Do these patterns mean anything to you? Absolutely. They can guide you towards insurers that offer excellent service without breaking the bank.
“I didn’t believe customer service could be this bad until I switched to a budget provider. Lesson learned!” – Mark T.
Meanwhile, insurance giants like Nationwide receive accolades for their broad range of coverage options and competitive pricing. What’s the takeaway here? No matter where you live in North Carolina, comprehensive reviews can be a goldmine for insights.
Recent Trends in Insurance Rates
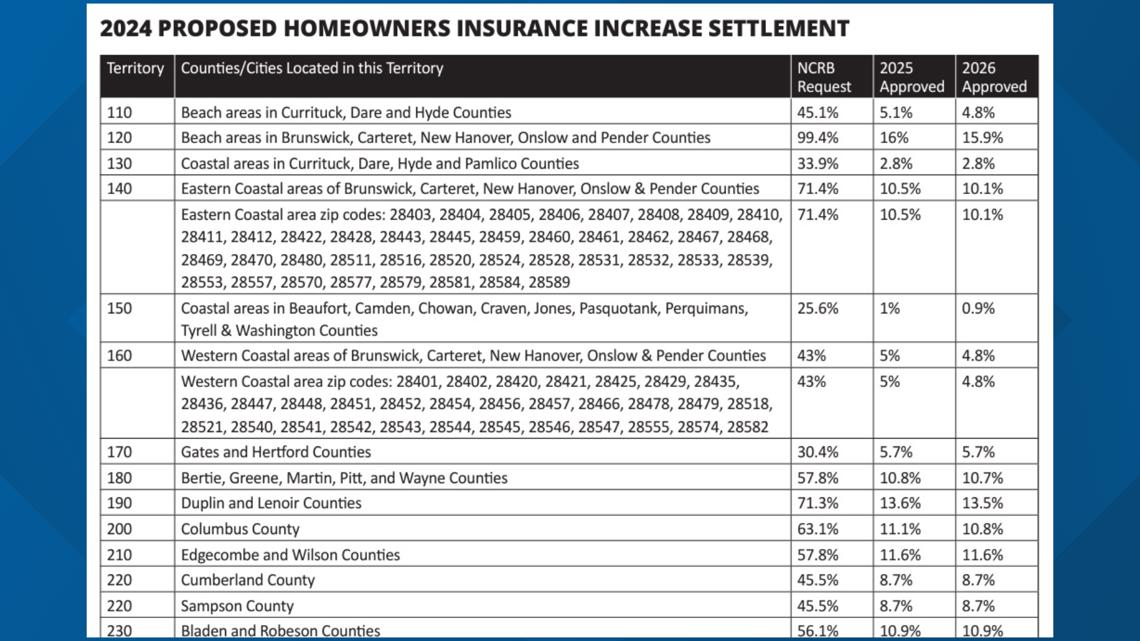
Have you ever noticed your insurance bill creeping up every year? You’re not alone. Insurance rates in North Carolina have been on a rollercoaster ride lately. Let’s break down what’s happening.
In recent years, North Carolina’s insurance rates have fluctuated due to a mix of economic pressures and emerging risks. According to state data, average car insurance premiums started climbing faster than the national average. AND it doesn’t stop with auto insurance – home and health insurance rates are also on the rise here.
The Surge in Insurance Premiums
So, why are we seeing this surge? It’s simple: the economy. Inflation has put pressure on insurers, forcing them to increase rates to maintain profitability. Add unforeseen events like hurricanes and rising medical costs and you have the perfect storm for increasing premiums. In 2022, North Carolina faced a 3% increase in average health insurance rates, primarily driven by higher healthcare spending.
Impact of Economic Factors
Here’s the deal: the economy plays a massive role in determining insurance rates. When inflation hikes up the cost of repairs, medical expenses, or rebuilding homes, insurers pass those costs onto you. The Federal Reserve reported a notable inflationary spike in 2022, which impacted many sectors, including insurance.
- Auto insurance saw a 5% rise due to costly vehicle repairs.
- Home insurance increased by 4% as building material prices soared.
- Health insurance premiums adjusted upwards by 3%, catching up with elevated medical service demand.
Shifting Trends Over the Past Years
Over the past few years, one of the key shifts in insurance trends has been the increased reliance on data analytics. Companies are using more and more sophisticated methods to assess risk and set prices. We’re also seeing more customized policies catering to individual needs—gone are the days of one-size-fits-all. For instance, usage-based insurance models where premiums are based on driving behavior have gained traction. This trend alone could make a big difference in how much you pay.
Pro Tip: Keep an eye on tech-driven policy offerings. They’ll likely save you money where traditional methods fall short.
Final Summary
As you’ve seen throughout this guide, getting the best insurance rates in North Carolina isn’t just about luck or taking the first offer you receive. It’s about strategic research, understanding your needs, and leveraging comparisons to find extraordinary deals. With this newfound knowledge, you’re well-equipped to tackle the insurance market in NC like a pro and secure the coverage that best suits you and your budget.
FAQ Section
What are the different types of insurance available in North Carolina?
North Carolina offers various insurance types including auto, home, health, life, and business insurance, each catering to different needs and offering unique benefits.
How do local regulations affect insurance rates in North Carolina?
Local regulations can influence insurance rates dramatically through oversight on minimum coverage requirements and government-mandated policies.
What factors most influence the cost of insurance in NC?
Key factors include your credit score, driving record, location, age, and the type of coverage you choose.
How can I lower my insurance rates in NC?
Consider bundling policies, increasing your deductible, maintaining a good credit score, and shopping around to compare quotes from different providers.
What are common mistakes to avoid when searching for insurance?
Avoid underestimating coverage needs, overlooking customer reviews, and not reading the fine print in your policy agreements.